
Rule 56 default judgment against SARS: lessons from Virgin Mobile
SARS missed its Rule 31 deadline by more than a year, then filed five business days after receiving a Rule 56 notice. In CSARS v Virgin Mobile, the Supreme Court of Appeal ruled that this late filing cured the default. Here is what the judgment means for taxpayers seeking default judgment against SARS
Rules 31 to 33: how the courts treat new grounds in tax appeals
SARS rebuilt its case mid-appeal and lost at the Supreme Court of Appeal. Two taxpayers raised new grounds late and kept them. Three recent judgments show where Rules 31 to 33 draw the line, and why the objection you draft today decides the appeal you can argue later.
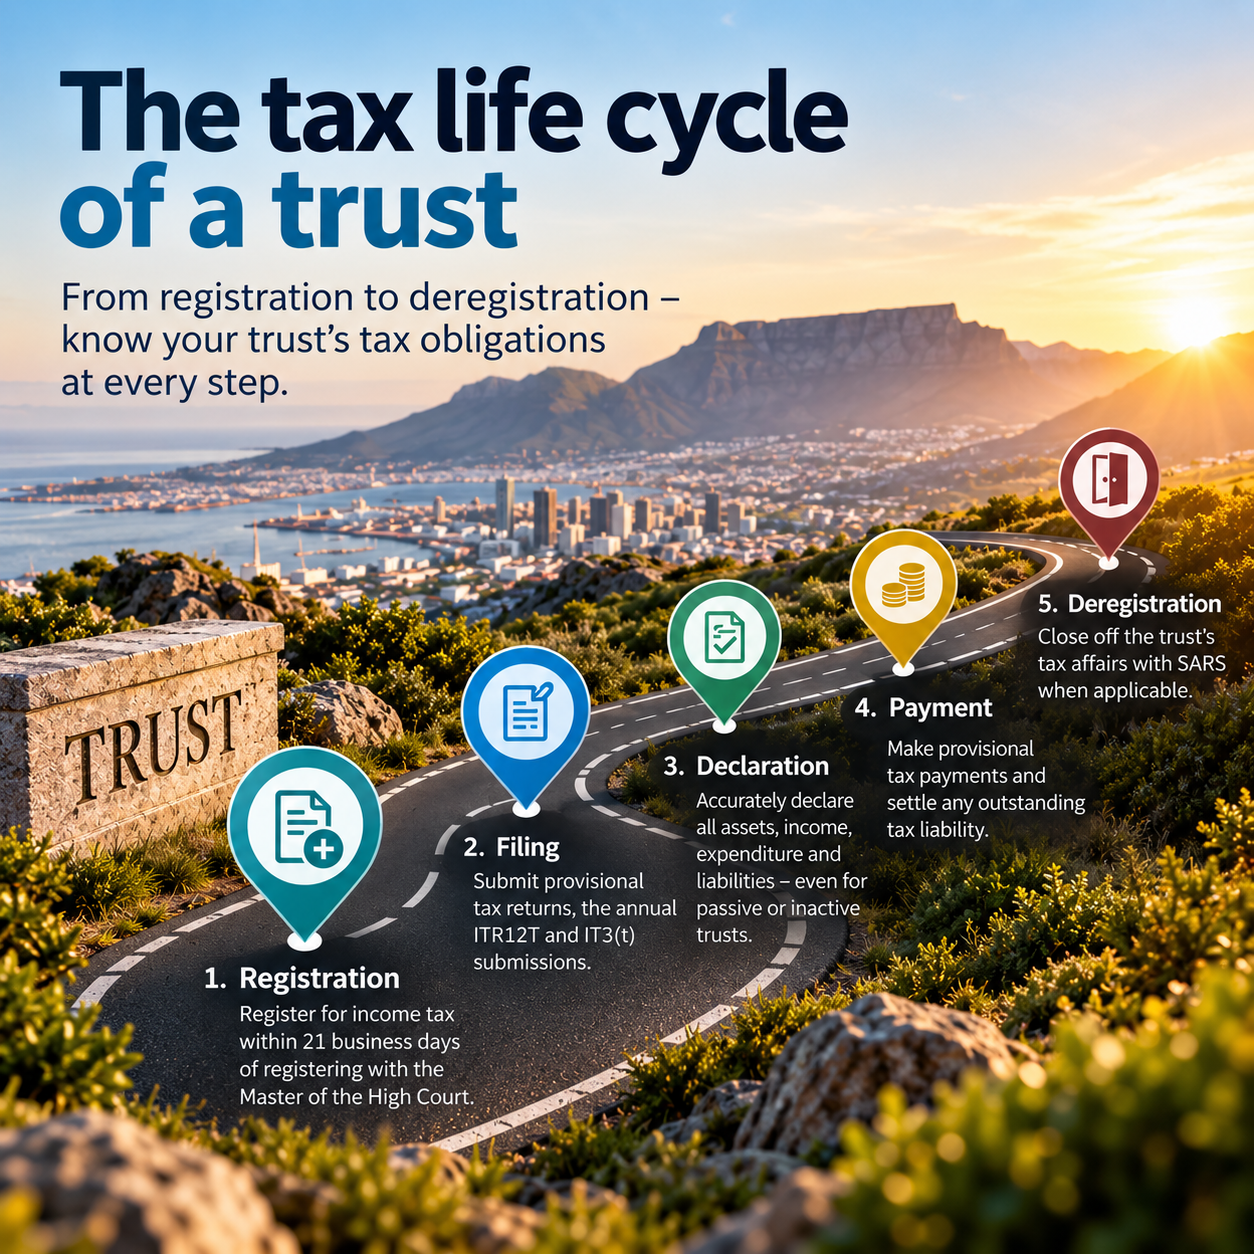
The tax life cycle of a trust
A trust’s tax obligations do not begin and end with the annual tax return. From registration and provisional tax to annual filing, IT3(t) reporting, accurate disclosure, payment and eventual deregistration, every stage carries specific compliance responsibilities. Importantly, even passive or economically inactive trusts must file annual returns and fully disclose their assets, liabilities and relevant financial information.
Buying a Business vs Buying Shares: Tax Choices Explained
A R50 million business sale. An R18 million tax bill due in February. The first payment only arrives in May. When a business changes hands, tax shapes the deal. Find out why selling assets or shares changes everything, and the six questions every buyer and seller must answer before signing.
Role of tax practitioner in a tax court
Can a tax practitioner represent a taxpayer in the Tax Court? Two recent judgments say yes, because the Tax Court is not a court of law. But the right to appear is only the start. Find out what the appeal process involves and why specialised litigation skills now matter more than ever.
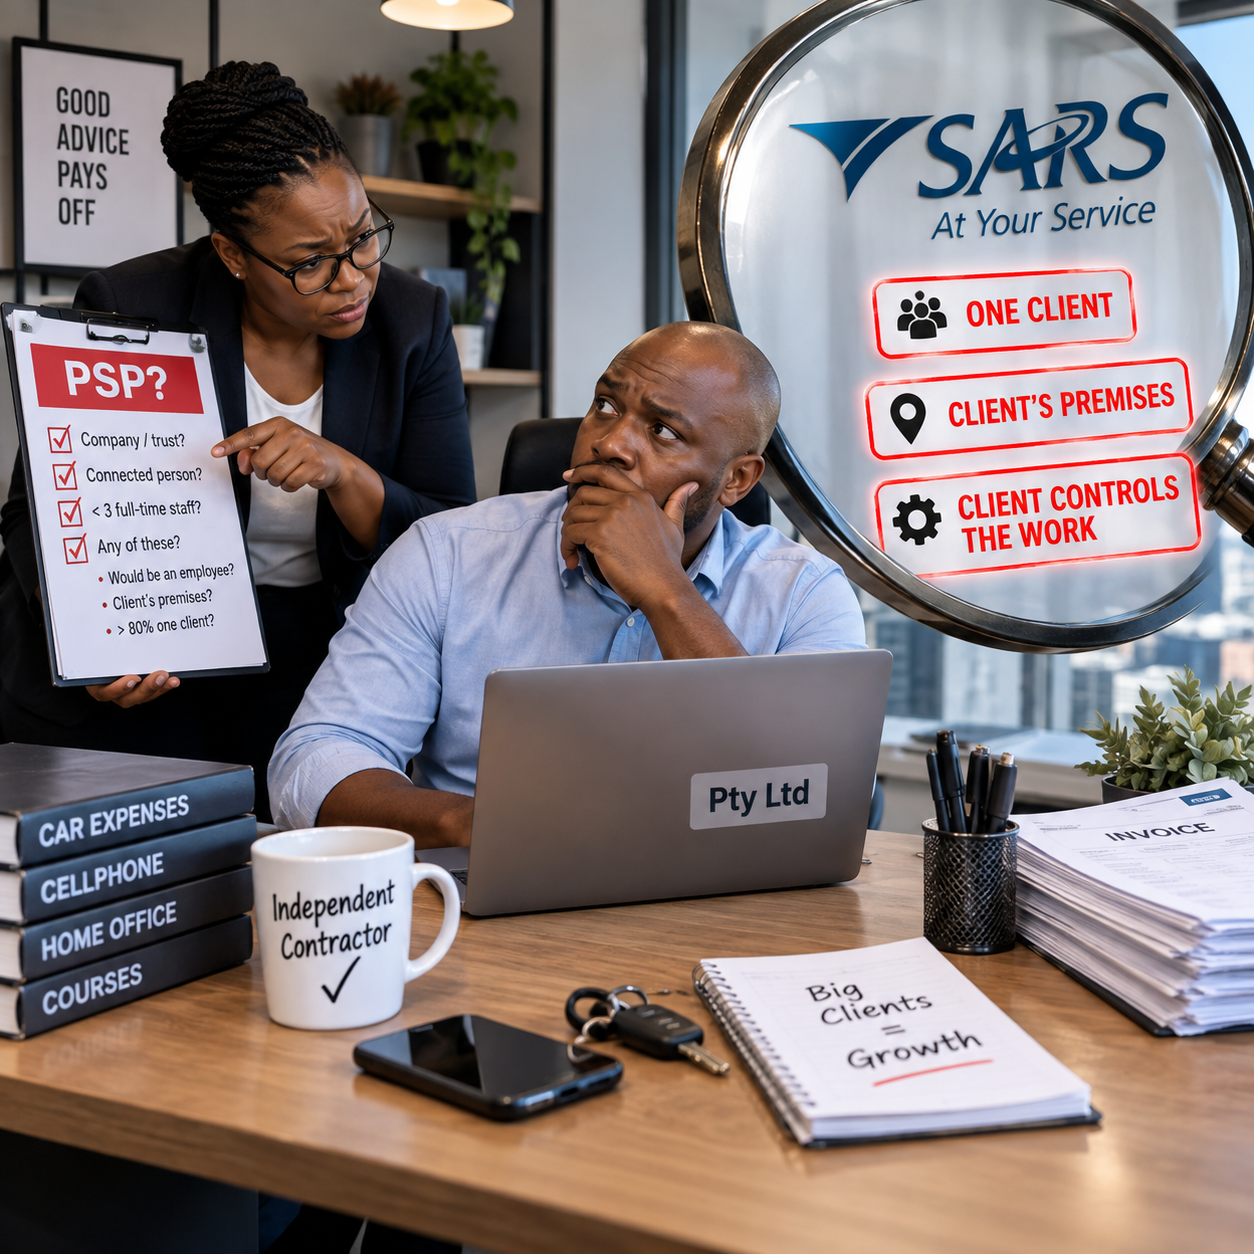
Personal Service Provider Rules: When SARS Says You Are an Employee
Your payroll clients are the ones exposed. Pay a one-man company for services and you may be an employer who should have withheld PAYE at 27%. Get it wrong and the shortfall, the 10% penalty and the interest follow the directors personally. Here's how to spot it first.
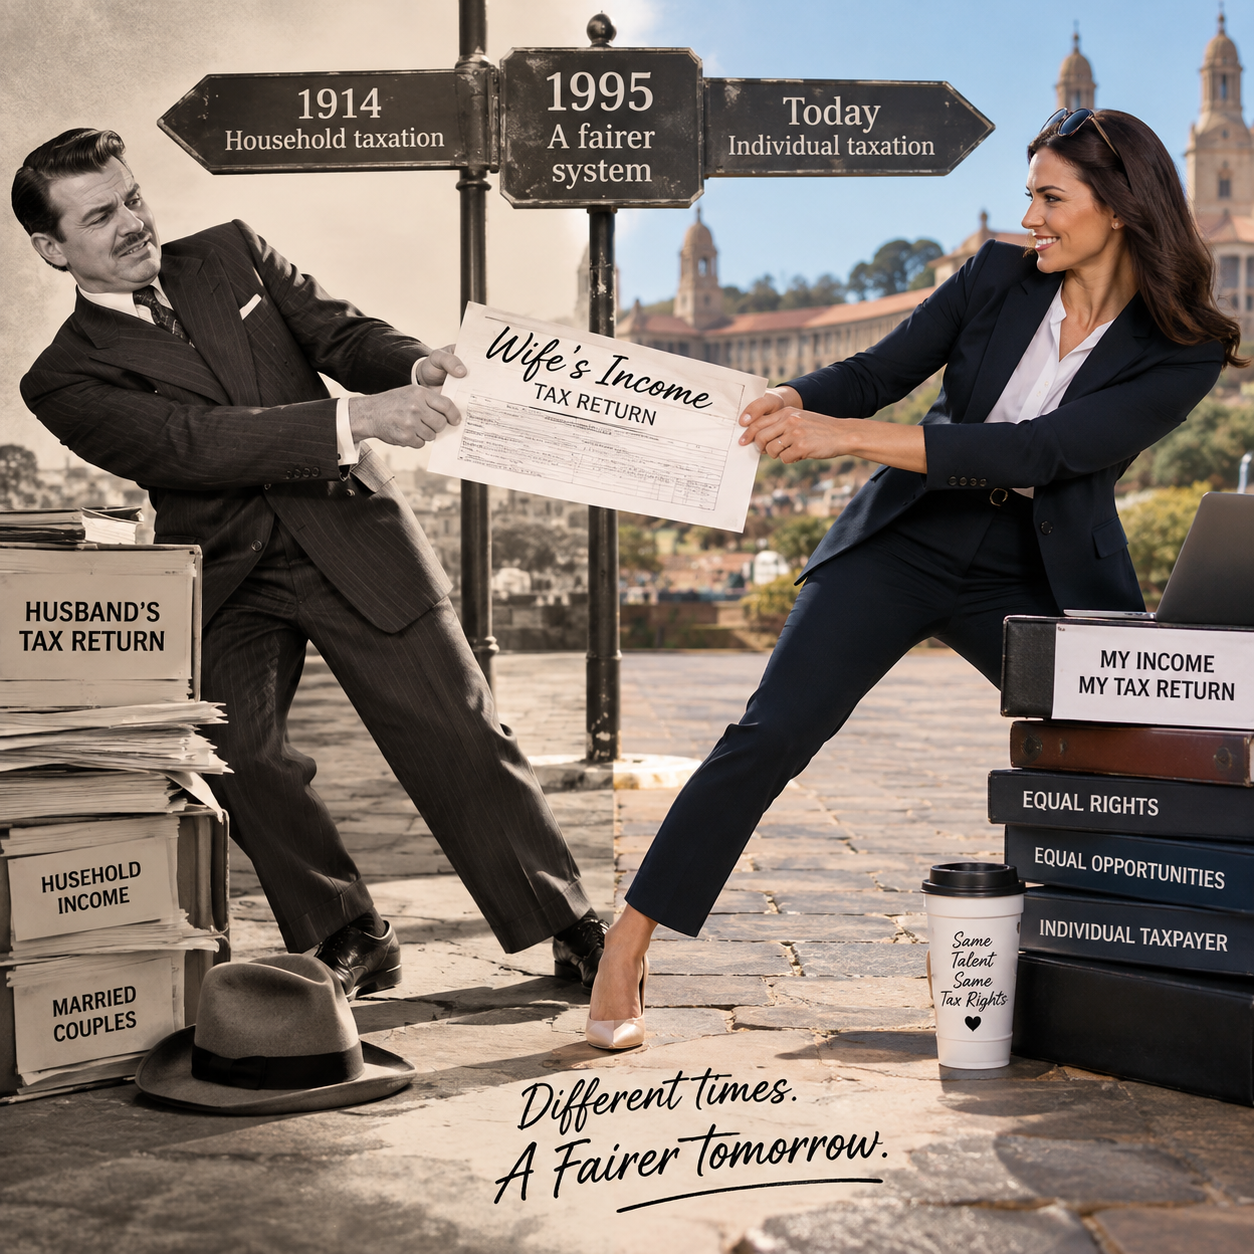
History of Submitting Tax Returns by Female Spouses: Income of Married Women
There was a time when a married woman's income was not her own, at least not for tax purposes. It was deemed to accrue to her husband and declared on his return. Here is the short history of how South African tax law moved from taxing the household to taxing the individual.

The payment of lobola: The Tax consequences
Does paying lobola have tax consequences in South Africa? Discover whether lobola attracts donations tax, income tax, capital gains tax or VAT, and what accountants and taxpayers need to know about this important customary practice and SARS.
Six Tax Changes CIBA Asked Treasury to Amend
Six proposals in the 2026 draft tax Bills will land on your desk: a VAT charge for schools with no way to pay it, two rules backdated to Budget day, and a provisional tax penalty your client cannot escape. Here's what CIBA told Treasury, and what to check first.
SARS VAT e-Invoicing: What It Means for Your Practice
SARS is proposing a five-corner e-invoicing model where invoice data reaches it in near real time, from both the seller and the buyer. Rollout runs to roughly 2033, starting with large business. Here is how it works in plain language, and what it means for a small accounting practice.
Claiming input tax on Pre-Registration Invoices (Backdated VAT registration): What SARS Allows
SARS has backdated your client's VAT registration and the VAT bill looks frightening. It does not have to be. Invoices issued before the registration date can still support an input tax claim. See the four conditions SARS applies, and how to dispute the date under section 23(4)(b) of the VAT Act.
SARS Revised ITR12 eFiling Guide: 12 Changes That Bite
SARS has issued a revised ITR12 eFiling guide, and it changes the way you work. Biometric login checks. A read-only auto-assessment waiting room. A Declaration Questionnaire with a 24 working hour deadline. OTPs on banking changes, with penalties up to R16 000 for a false declaration. Here are the twelve changes practitioners need to action before the 23 October filing deadline.
Construction VAT: Why It Never Matches Revenue, and the Mistake SARS Waits For
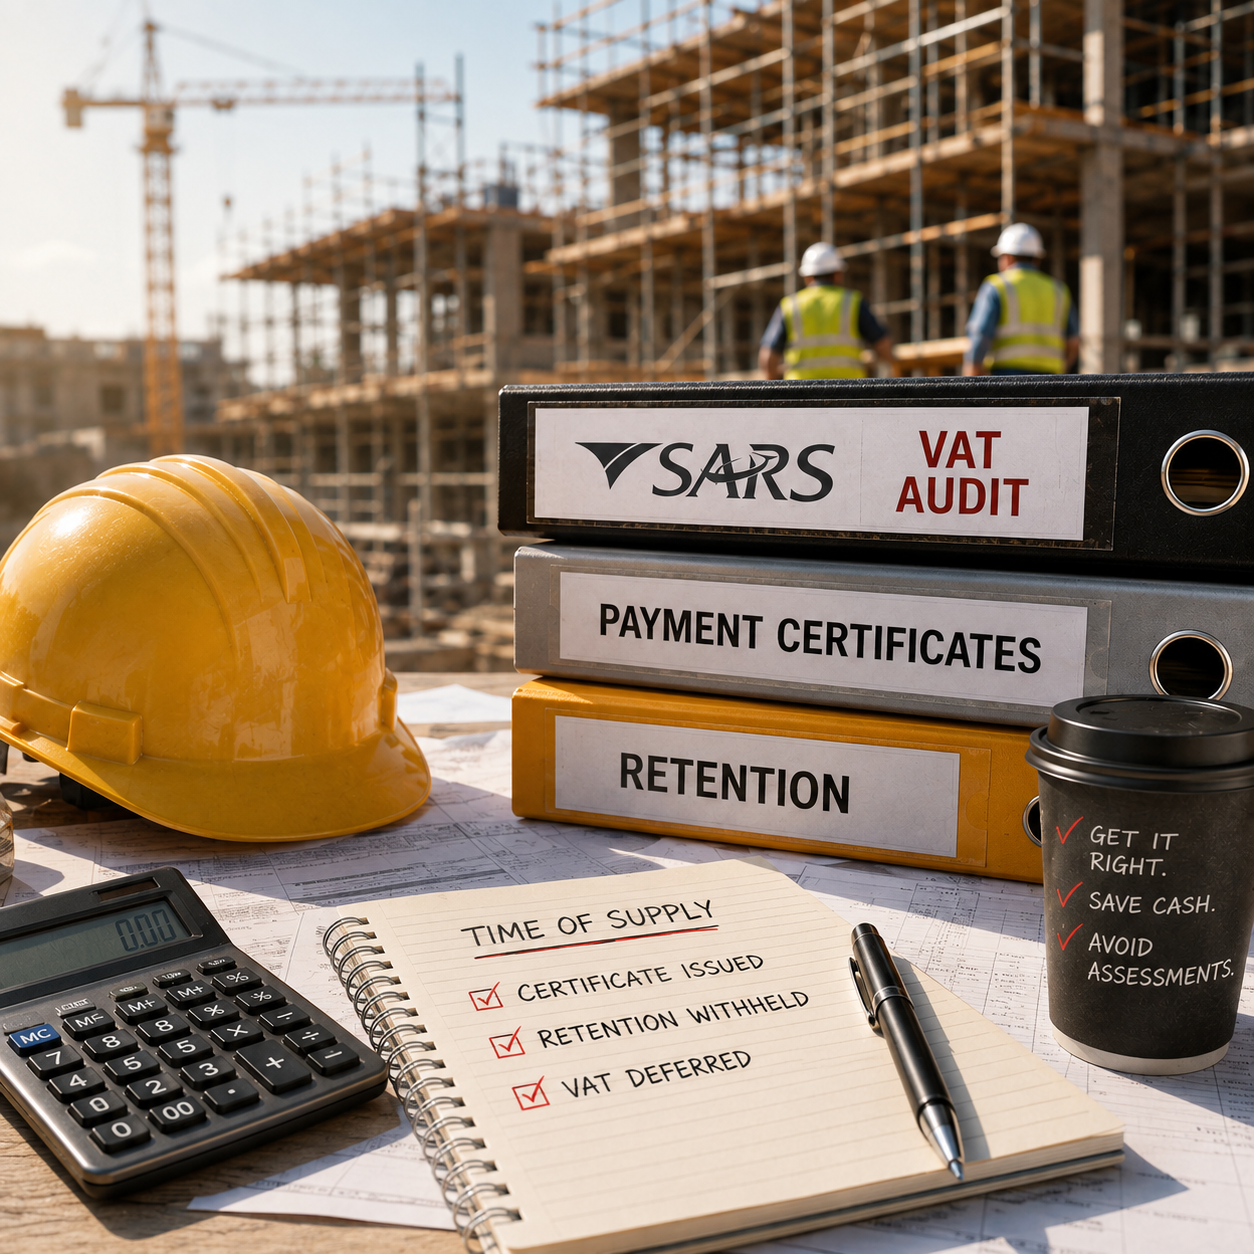
Your construction client's VAT will never match his revenue, and that is correct. Output VAT runs on the payment certificate under section 9(3)(b), not on when the accounts recognise the sale, so filing it off the revenue journal is the exact error SARS audits for. This article shows how the two clocks work, why retention VAT is deferred, why a refund month is normal, and how a firm can package the fix as a service clients pay for.
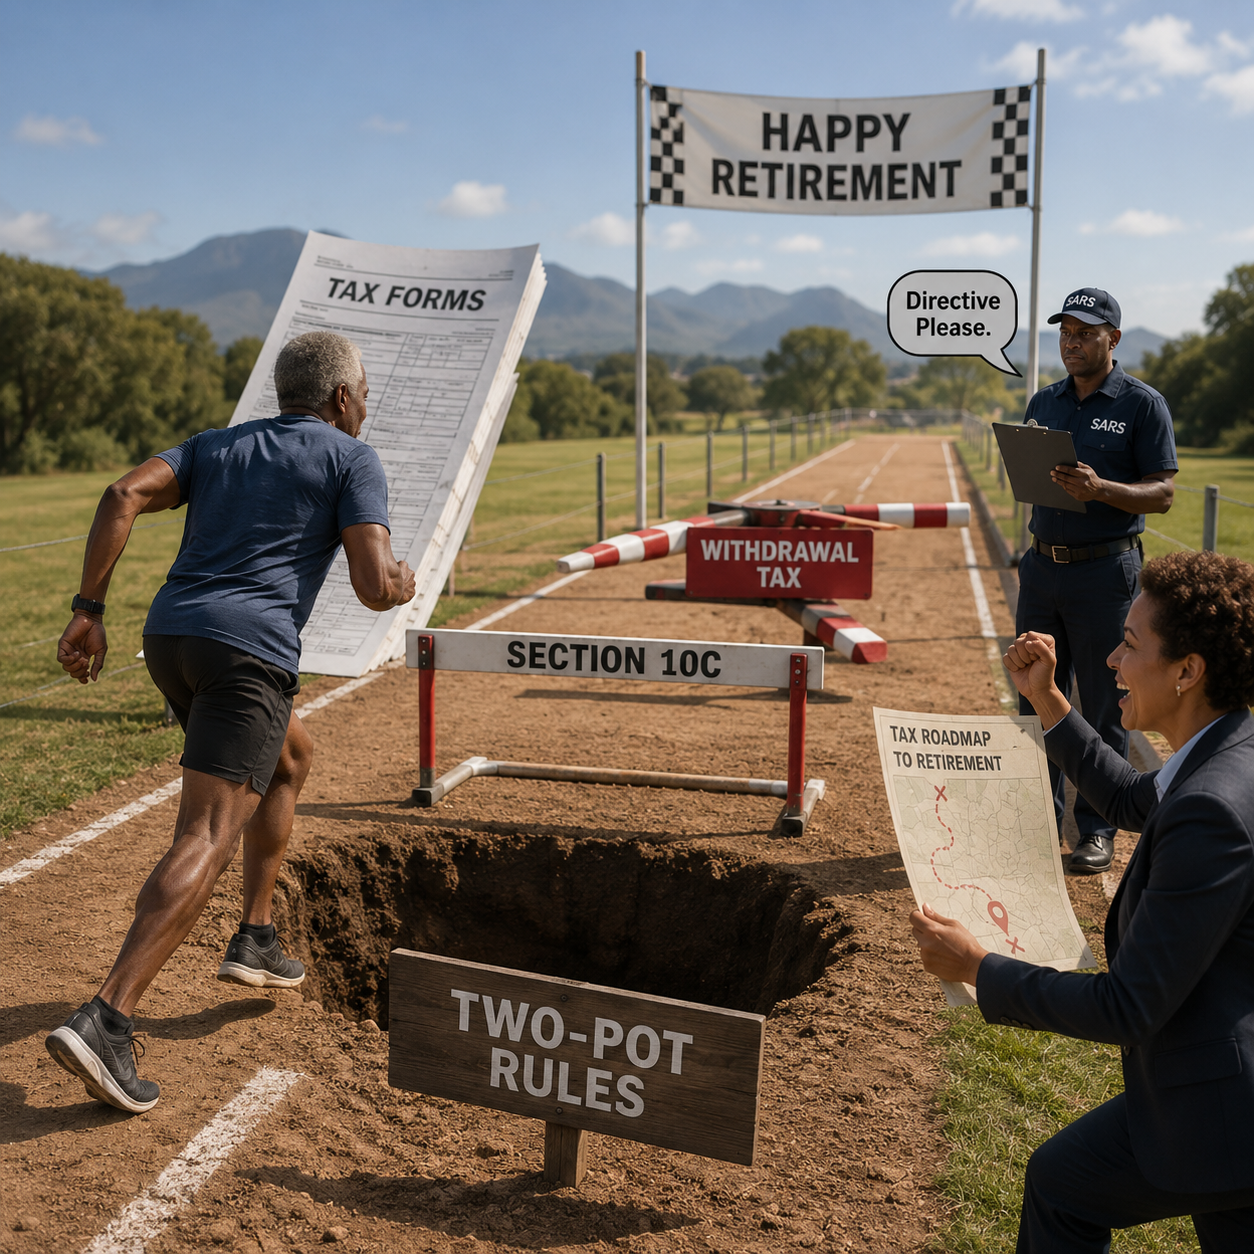
Retirement Fund Tax in South Africa: 2026/27 Rules Explained
Retirement fund tax can be confusing, but it doesn't have to be. This practical guide explains every stage of retirement fund taxation, from contribution deductions and two-pot savings withdrawals to retirement lump sums and annuity income. Updated for the 1 March 2026 tax changes, it also highlights key SARS resources and the seven costly mistakes accountants and taxpayers should avoid.
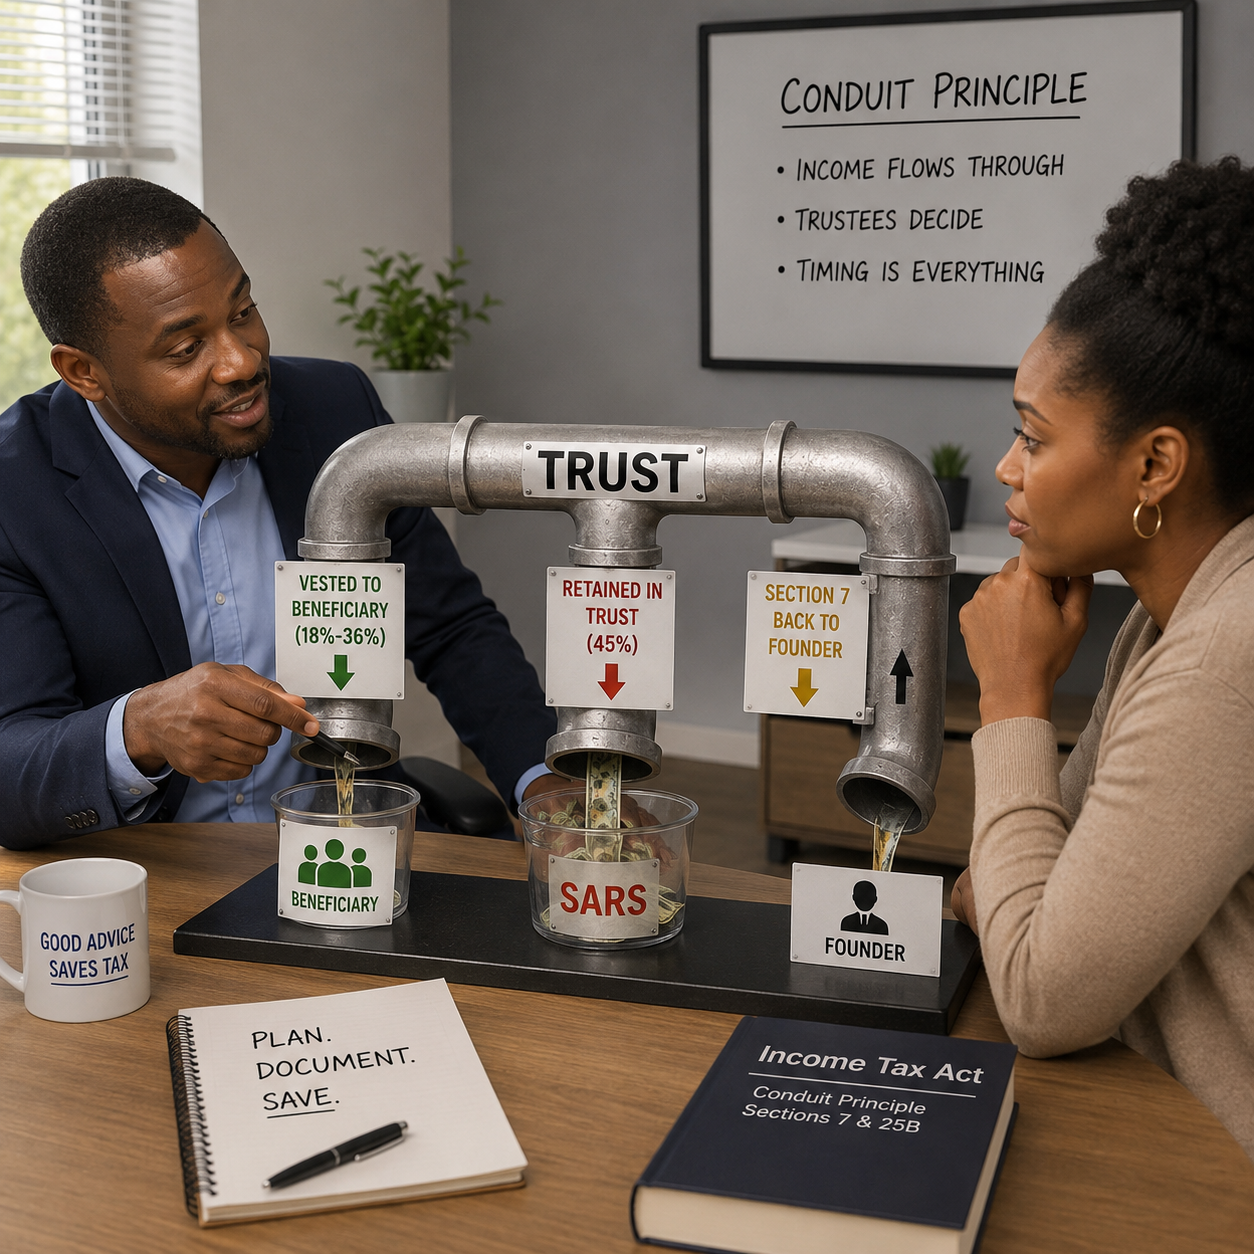
The Biggest Trust Tax Myth: Trusts Don't Save Tax. You, as a Tax Practitioner Do.
Most clients think a family trust automatically saves tax. It doesn't. Without the right trustee resolutions, correct timing and proper planning, a trust can end up paying a flat 45% tax instead. This article explains the three rules every accountant needs to master, the conduit principle, Section 7C and capital gains tax, and shows how a few simple decisions can save clients thousands while keeping them on the right side of SARS.
Travel Allowance, Company Car or Reimbursement? The Tax Rules
A travel allowance on your payslip is not a tax-free perk. SARS taxes 80% of it through PAYE every month, and the only way to reduce that tax bill is with a valid logbook at assessment time. The same applies to company vehicles and reimbursive payments. Each arrangement has its own rules, its own thresholds, and its own consequences when those rules are ignored. This guide explains exactly how each one works and what your clients need to do right now.
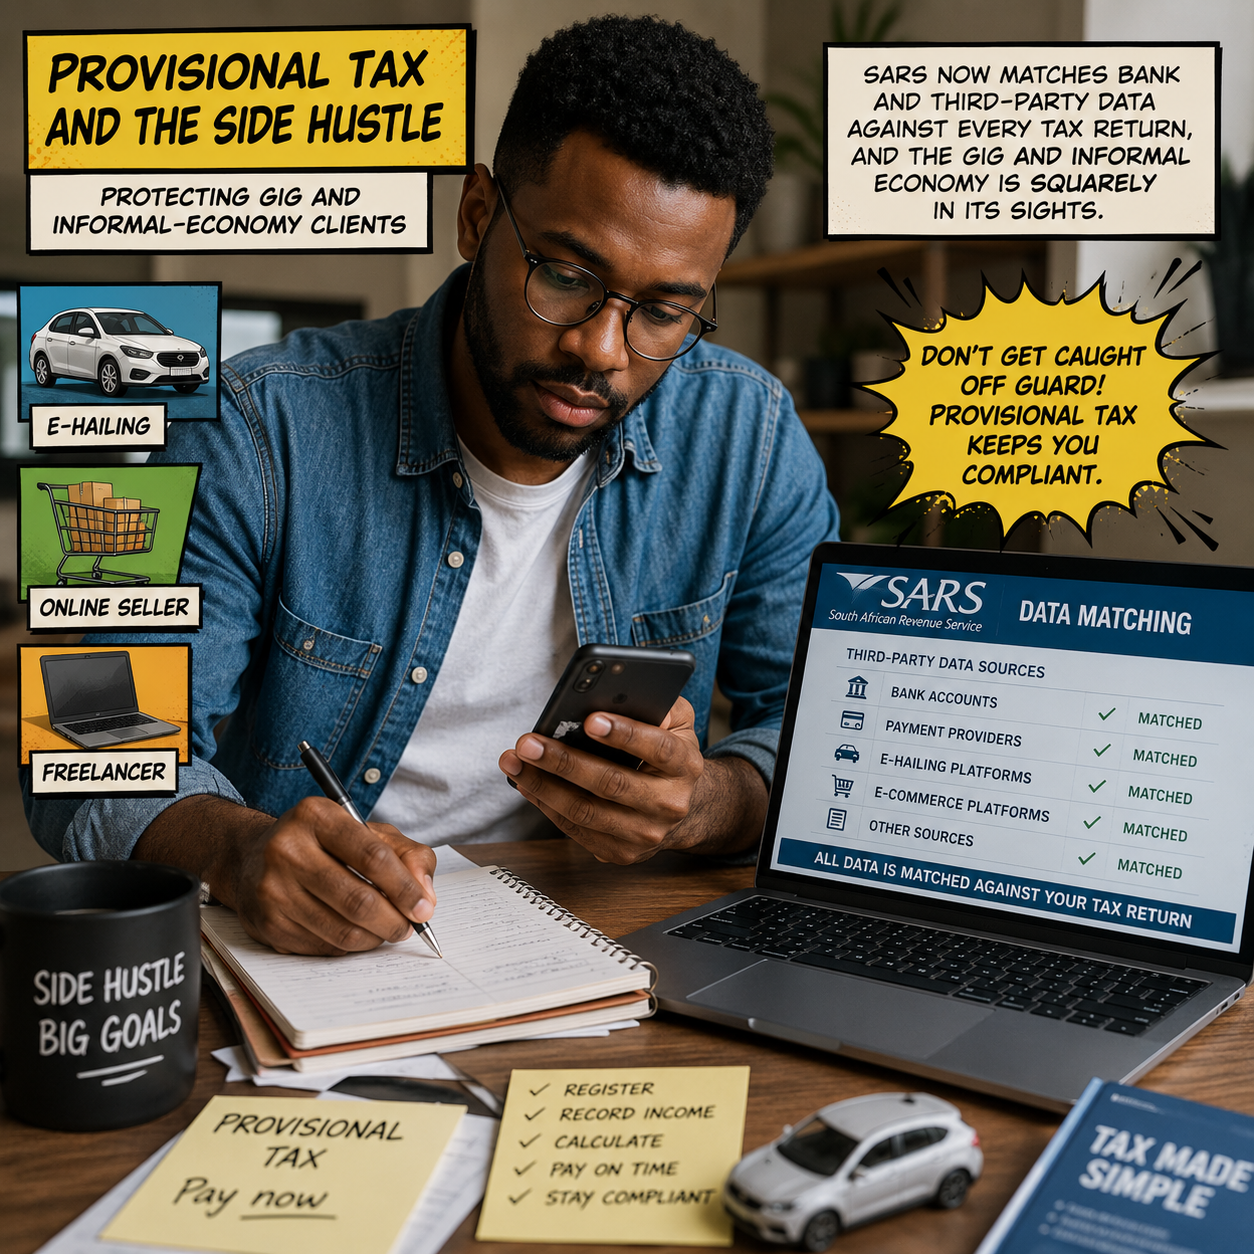
Provisional Tax and the Side Hustle: Protecting Informal-Economy Clients
SARS now matches bank and third-party data against every tax return, and the gig and informal economy is squarely in its sights. For accountants, this is both risk and opportunity: act early, keep these clients compliant, spare them penalties and estimated assessments, and turn a once-a-year scramble into a recurring advisory service worth charging for.
New Tax Directive Rules: What Fund Administrators Need to Know
From 17 April 2026, SARS updated the tax directive system in ways that directly affect your retirement clients. The biggest change: the lump sum threshold increased from R247,500 to R360,000, meaning more clients can now take their full retirement benefit without being forced to annuitise. Here is what else changed and what it means in practice.
PAYE and VAT Registration Issues, What You Need to Know and Do
Your VAT or PAYE application did not fail because the process is broken. It failed because of four mistakes SARS sees on almost every rejected application. At a recent stakeholder meeting, SARS named them out loud. Here is what they said, and what to fix before your next submission.
A Taxman’s Casebook: Debt forgiveness, debt provisions and write-offs
Most businesses assume they can only claim a tax deduction on a bad debt once they have written it off or raised a formal provision. That assumption is costing them money. Under Section 11(j) of the Income Tax Act, where IFRS 9 is not applied to trade debtors, a 25% tax allowance kicks in automatically once a debt hits 60 days overdue. At 120 days, that rises to 40%. No accounting provision required. No subjective judgement call on whether the debt is "truly doubtful." If the debt is old enough, the relief is yours. Many businesses are quietly leaving this money on the table simply because no one told them the rules changed.
Claiming of medical tax credit in the 2026 tax-year
SARS has updated its guide on medical tax credits for the 2026 tax year, and there are a few things every taxpayer should know before filing. From the monthly credit amounts and who qualifies as a dependant, to the new Declaration Alert Questionnaire that could save you from a full audit, this article breaks it all down in plain language. If you pay medical aid contributions for a parent, spouse, or child, or if your dependant numbers have changed from last year, this is what you need to know before you submit your return.