
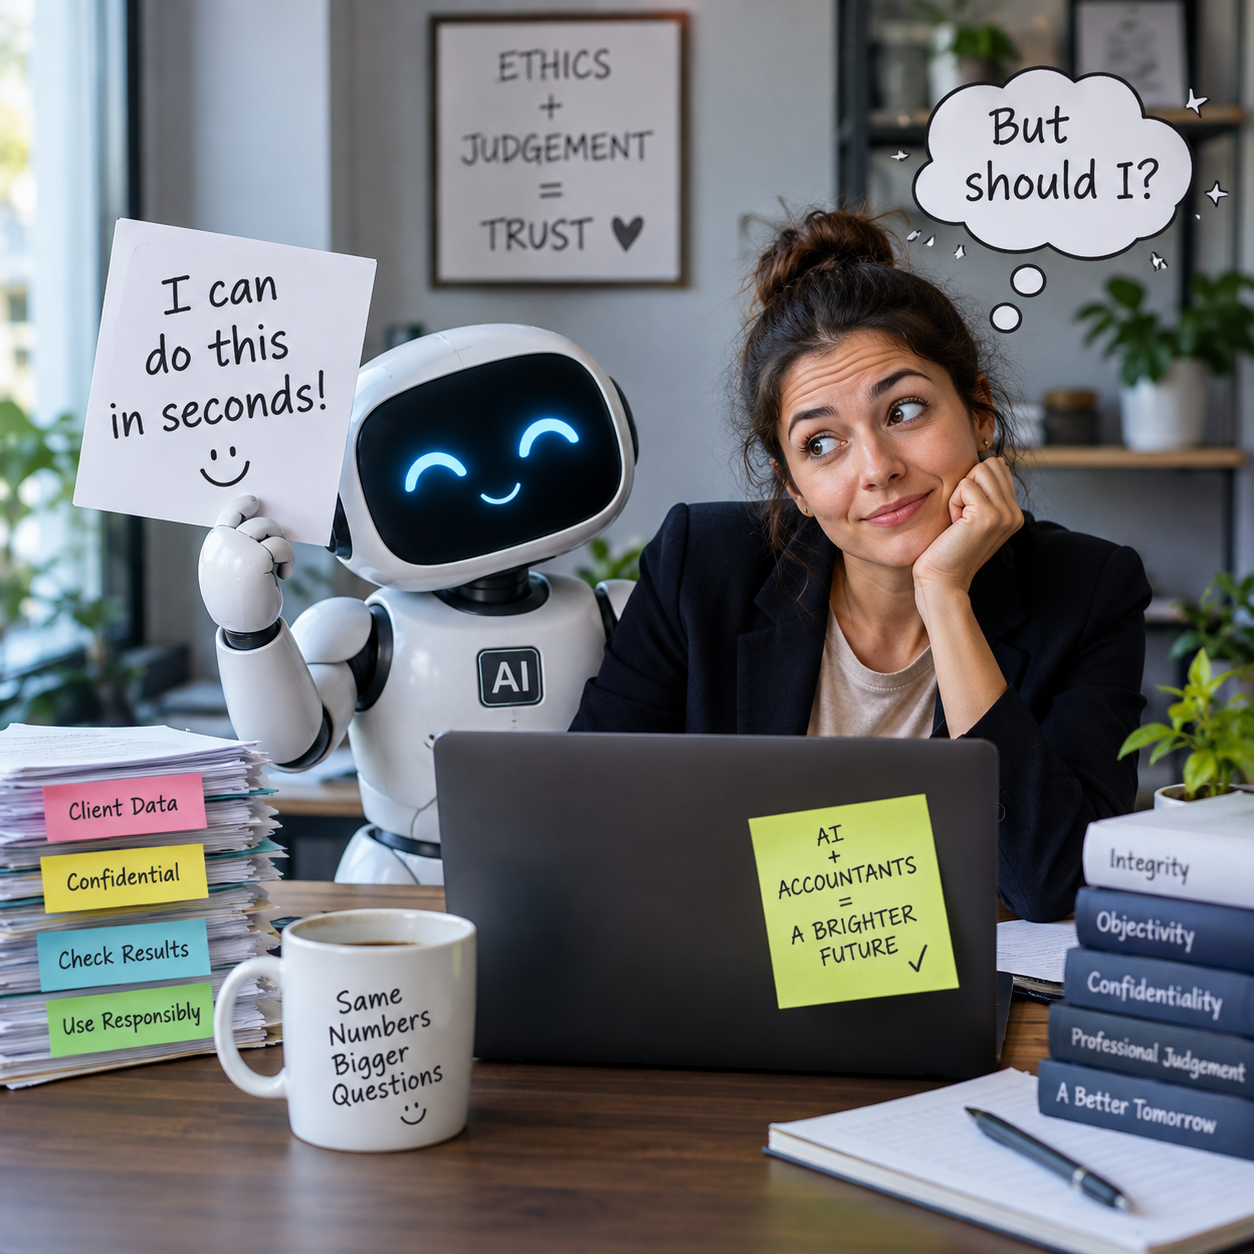
When Accountants Use AI: What Is Ethical and What Crosses the Line?
AI can help accountants work faster, but it also creates new risks. Uploading client information to an AI tool, accepting an automated result without checking it, or using confidential data without permission can lead to serious problems. Accountants still need to protect client information, check the work produced by technology and use their own professional judgement. Technology can assist with the work, but the accountant remains responsible for the final result.
Compliance, Risk and Ethics in Medical Practice Finances
This article looks at compliance, risk and ethics in medical practice finances. It explains common risks accountants and bookkeepers may face, including billing problems, unusual payments, poor recordkeeping and questionable client instructions, and how simple checks can help protect both the practice and your professional reputation.
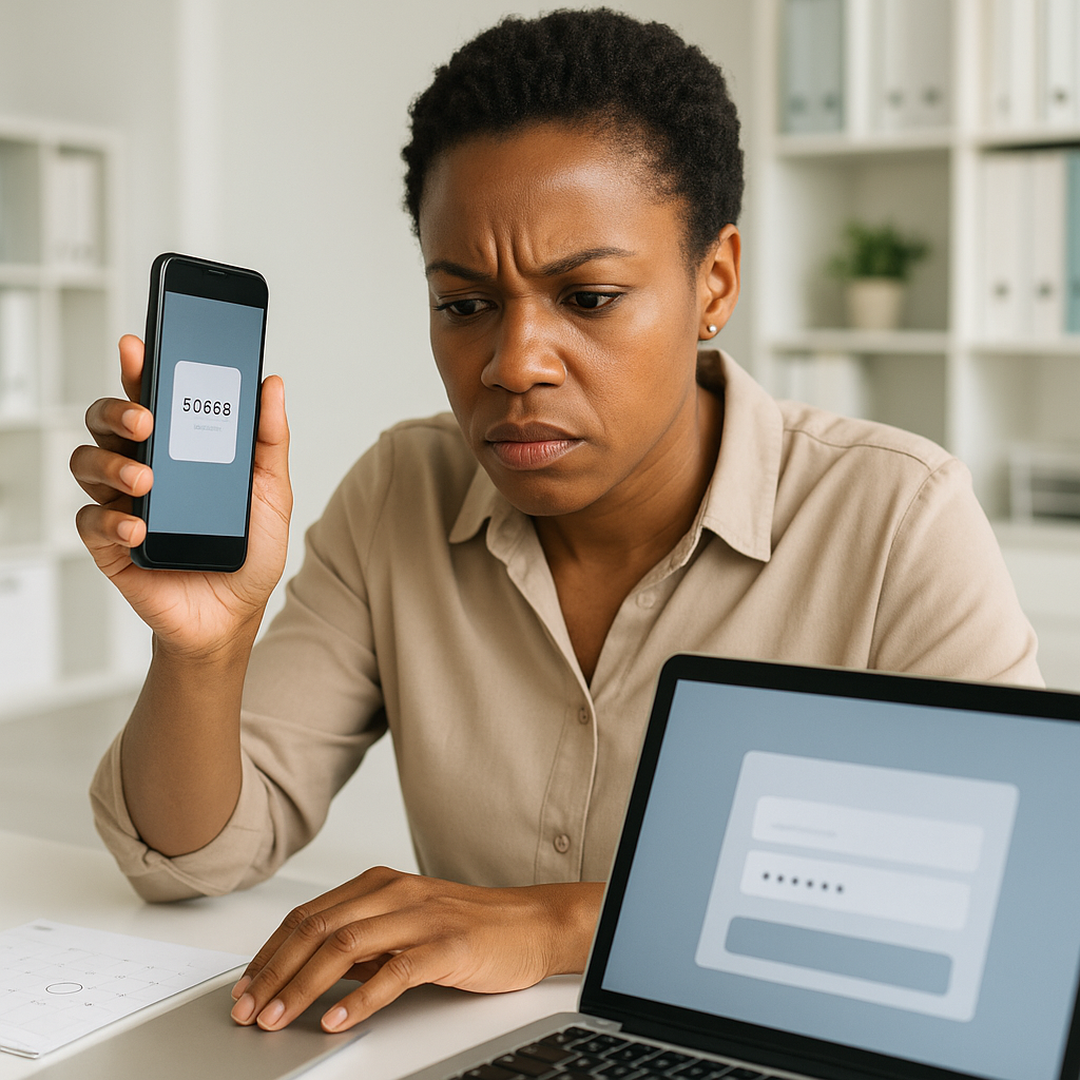
The Password That Kills Your Own Defence
It is 4pm on the 25th. The VAT201 is due, your client cannot reach their eFiling profile, and someone in your office asks them to send the login and the OTP. The return goes in on time. Eight months later a complaint arrives, and every submission on that profile is recorded as your client's, not yours. You cannot prove what you filed, or when. The borrowed password did not risk SARS catching you. It removed the only defence you had.
Why Ethical Members Report Themselves First
Dismissed, disputing it, and dreading what comes next? One email should not wait: the one to your Institute. CIBA's Terms and Conditions of Membership require members to disclose matters they are involved in, yes, even contested ones. Disclosure is not an admission, and it is not immunity either. The matter is still decided on its merits, but it removes the second breach, protects your credibility, and lets you sleep soundly knowing that however it ends, you acted ethically.
The Ethics Mistakes That Quietly Cost Accountants Clients, Fees, and Their Reputation
Most ethical failures in accounting do not begin with fraud or deliberate dishonesty. They begin with small decisions that feel harmless at the time. A client asks for a favour. A number is adjusted to solve a short term problem. Something does not feel right, but it seems easier to stay quiet than to create conflict. These moments may appear insignificant, yet they are often where reputations begin to unravel. When ethical boundaries become unclear, clients stop seeing the accountant as an independent professional and start seeing someone they can pressure, negotiate with, or blame when things go wrong.