This article will count 0.25 units (15 minutes) of unverifiable CPD. Remember to log these units under your membership profile.
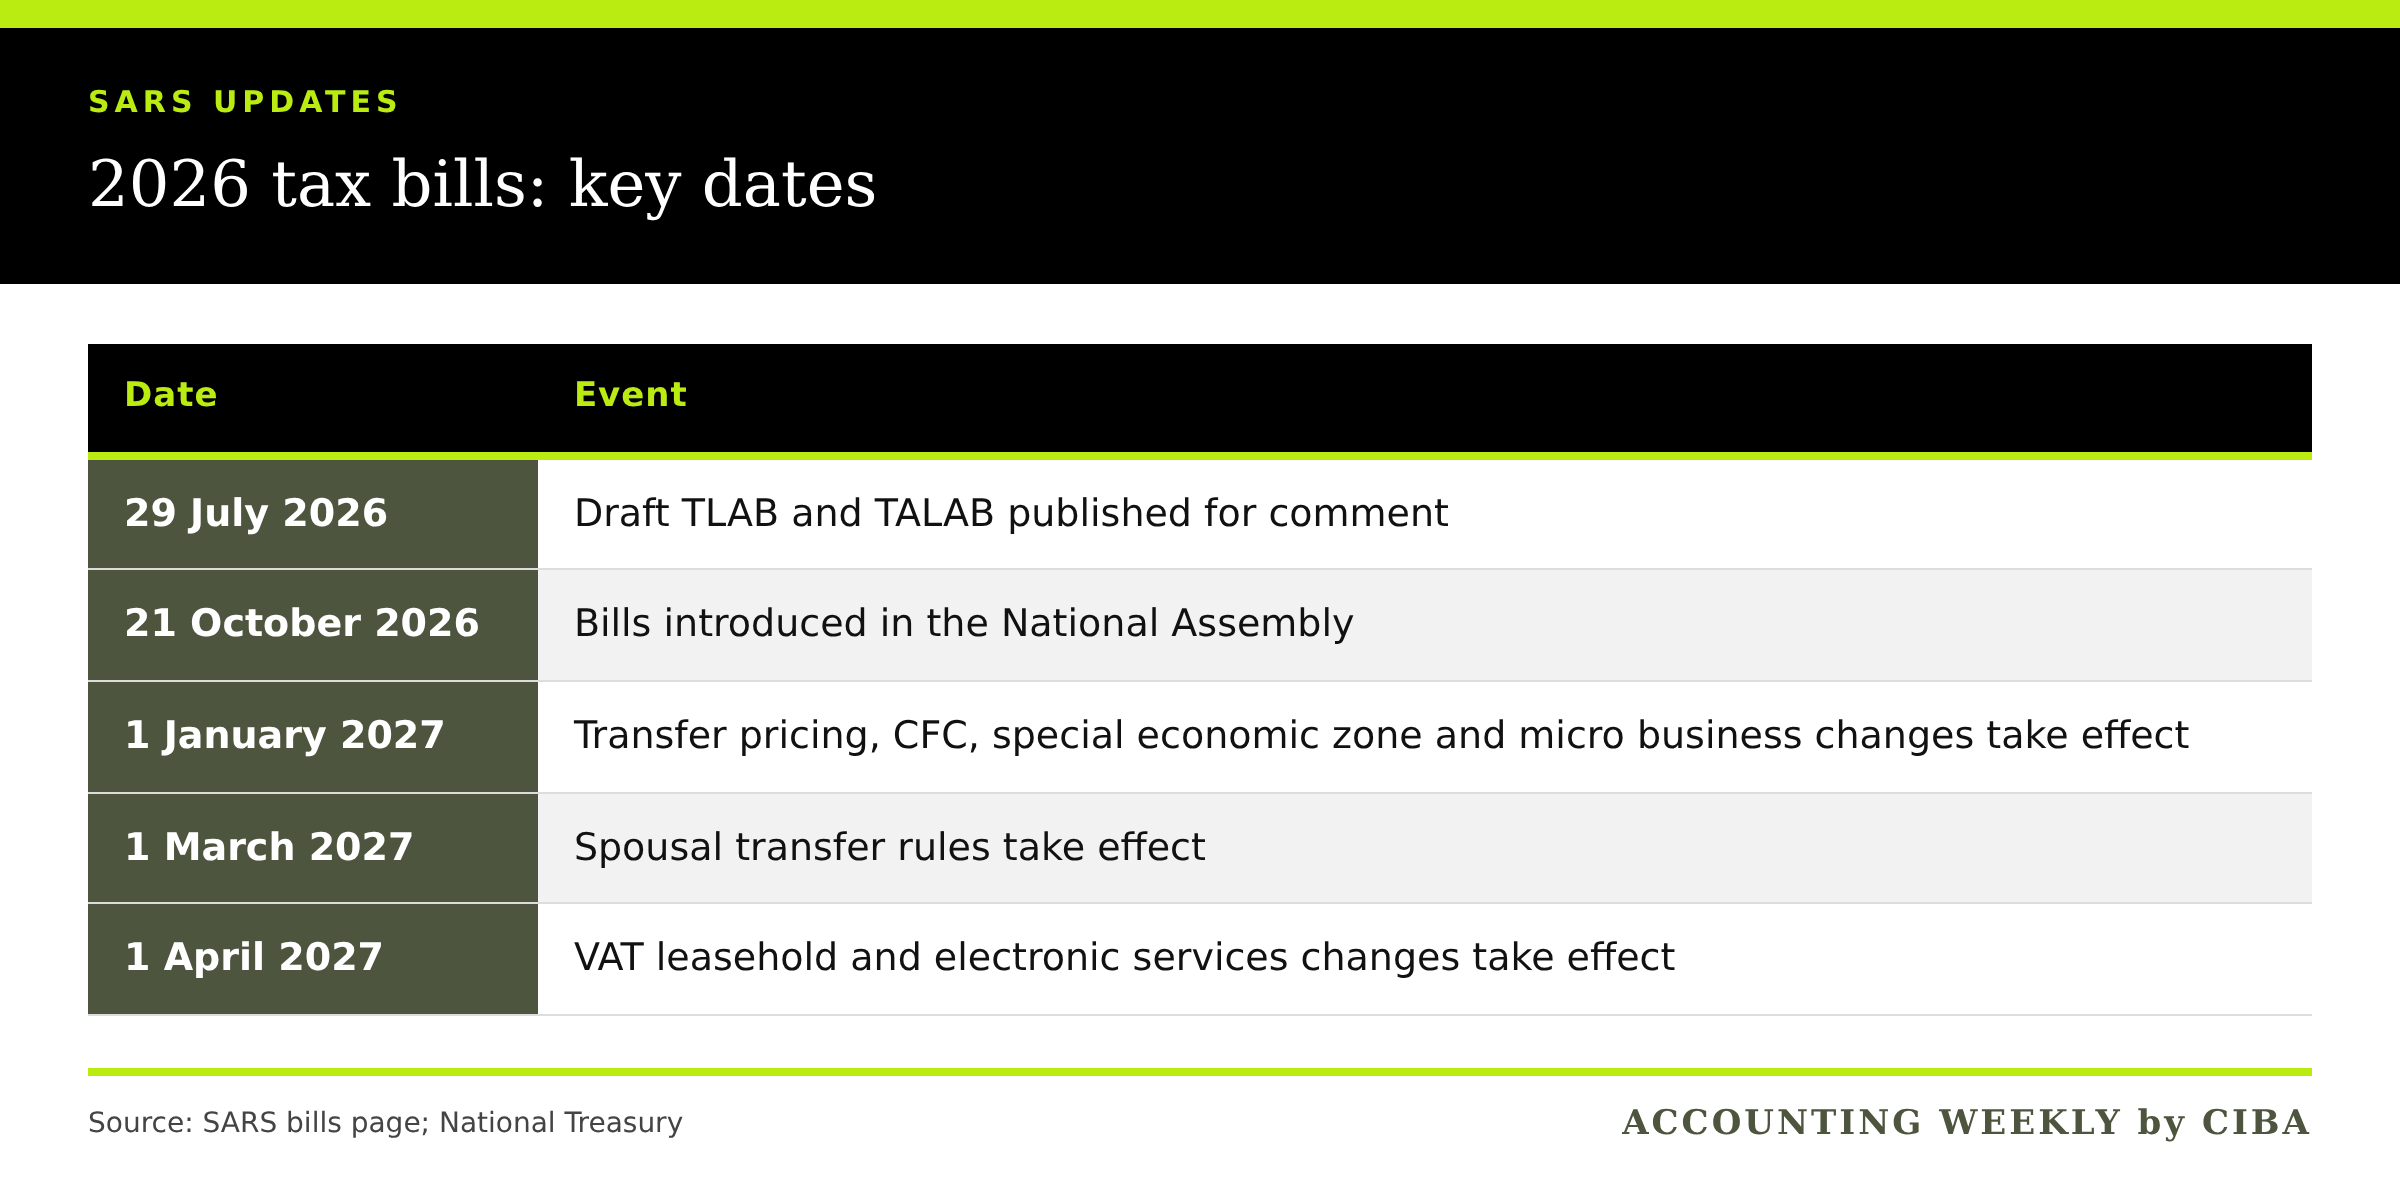
The Minister of Finance introduced three tax bills in the National Assembly on 21 October 2026. They are the Taxation Laws Amendment Bill [B32—2026], the Tax Administration Laws Amendment Bill [B33—2026] and the Rates and Monetary Amounts and Amendment of Revenue Laws Bill [B34—2026]. SARS has published all three on its bills page.
What changed
The bills move from draft to formal parliamentary stage. National Treasury published the draft TLAB and TALAB for comment on 29 July 2026.
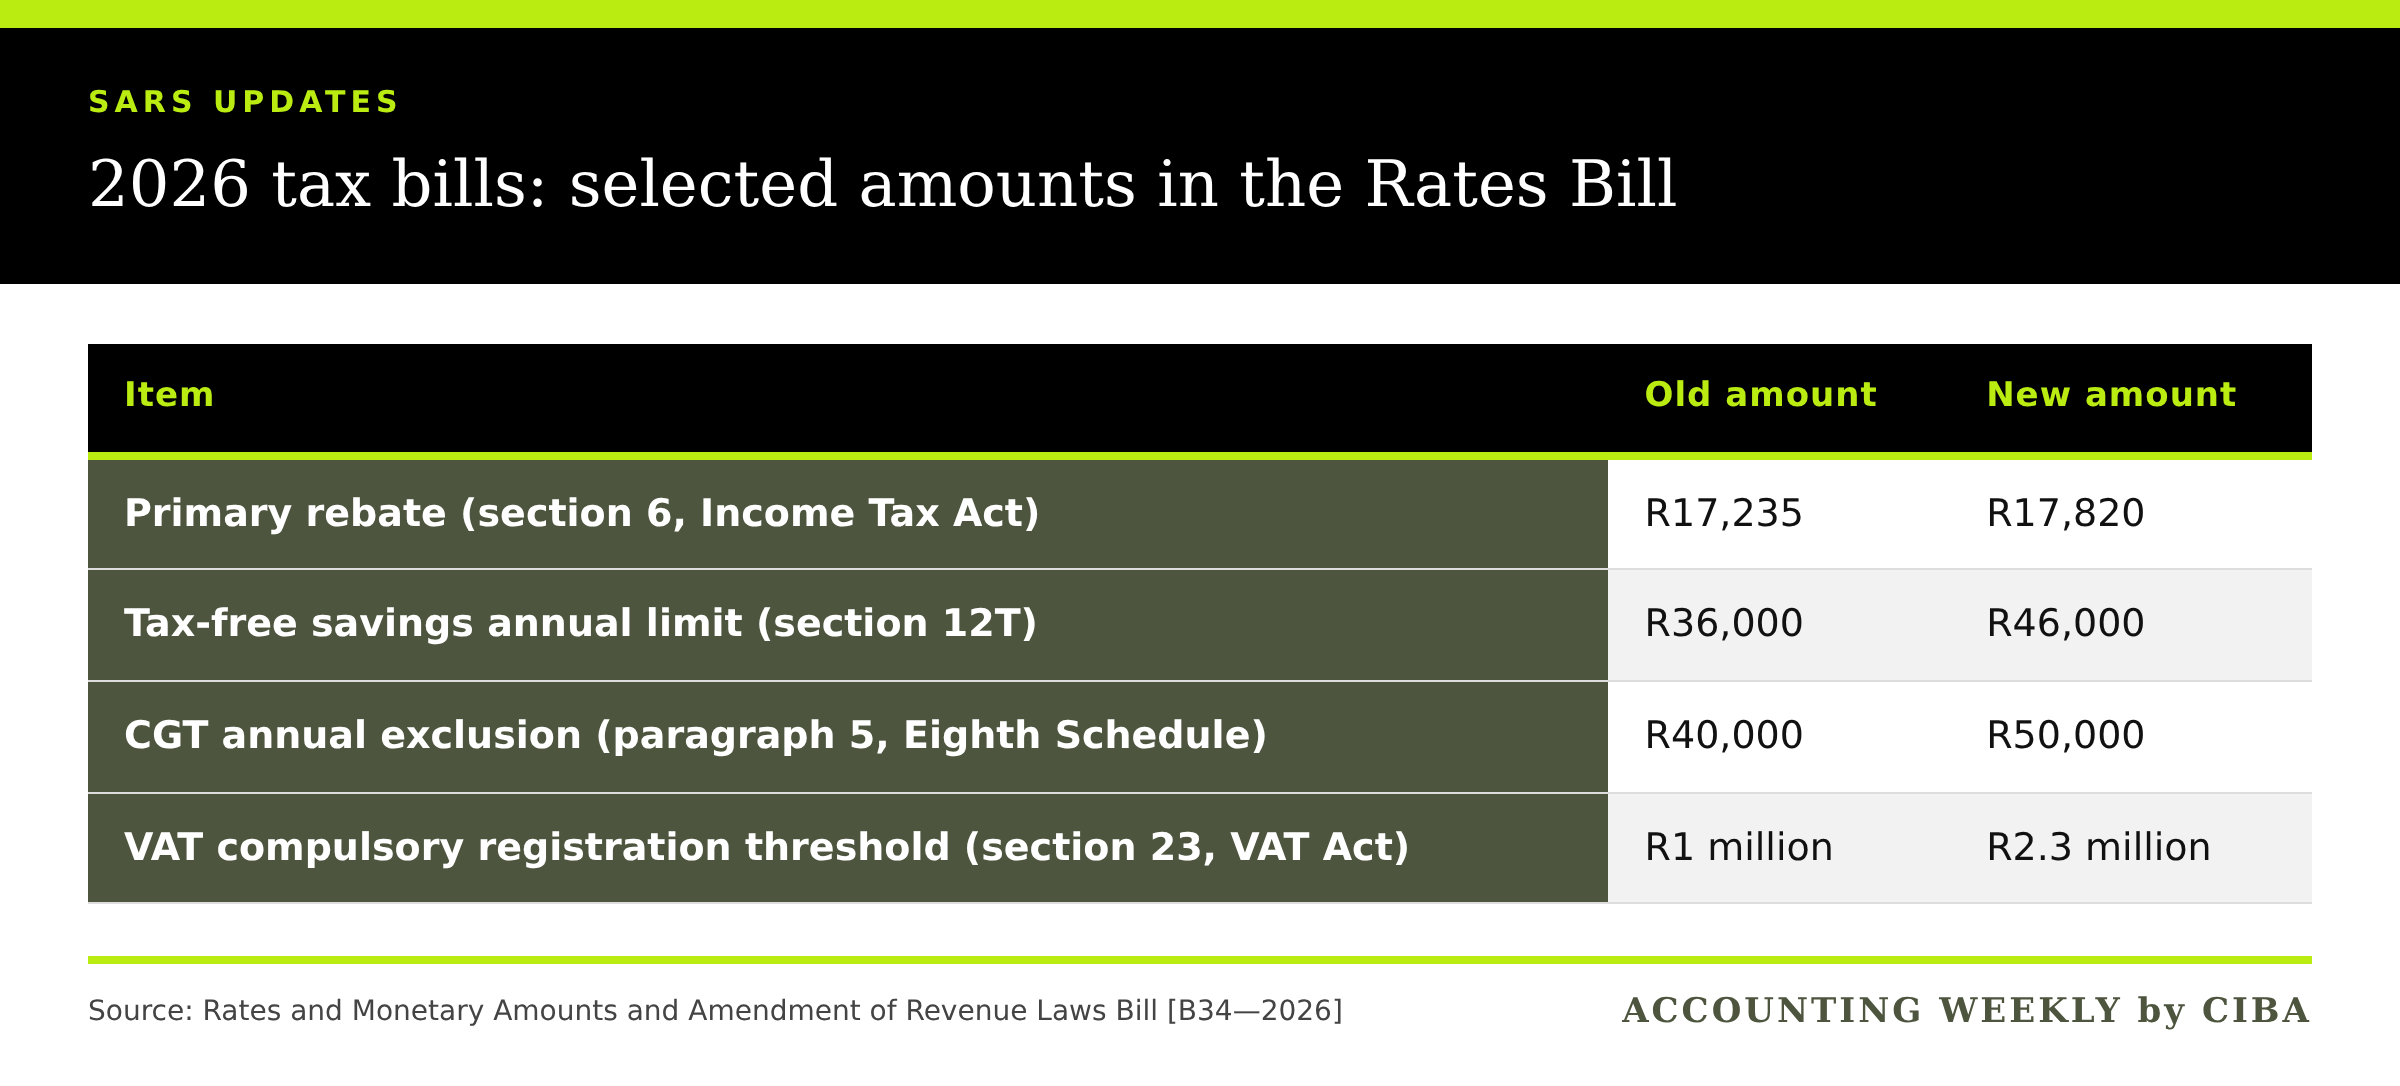
The Rates Bill sets new tax tables, rebates and thresholds, most of them deemed to apply from 1 March 2026. Selected amounts in the bill:
The TLAB covers, among other things:
Medical scheme fees tax credit extended to restricted medical schemes, with employer contributions to those schemes treated the same as contributions to registered schemes, from 1 March 2026.
Rewritten rules for asset transfers between spouses, for disposals on or after 1 March 2027.
The micro business election moves from the start to the end of the year of assessment, from 1 January 2027.
VAT changes for leasehold improvements and electronic services intermediaries, from 1 April 2027.
A mechanism under which a VAT rate change announced in a Budget takes effect on a date the Minister sets, for 12 months, subject to Parliament passing legislation in that period.
Accounting Weekly covered the TALAB explanatory summary on 19 October 2026.
Who it affects
Individual taxpayers, employers running payroll, VAT vendors and businesses near the VAT threshold, micro businesses on turnover tax, and companies with controlled foreign companies or operations in special economic zones.
What this means for accountants and finance professionals
The bill gives the new amounts legal force once passed. Check each clause's effective date before relying on a figure.
Once the bill is passed, clients with taxable supplies between R1 million and R2.3 million in a 12-month period will fall below the new compulsory VAT registration threshold. The change is deemed to apply from 1 April 2026.
If the bill passes unchanged, transfers between spouses made before 1 March 2027 fall under the current rules.
The bills may still change during the Standing Committee on Finance process.
Effective dates differ by clause, so check each clause before advising.
Key dates
What to do
Download the bills from the SARS bills page.
Compare the introduced TLAB and TALAB with the July drafts for clauses that affect your clients.
Diarise the 2027 effective dates.
Follow Accounting Weekly and the Standing Committee on Finance for amendments before the bills are passed.
Sources: SARS bills page, Taxation Laws Amendment Bill B32—2026, Tax Administration Laws Amendment Bill B33—2026, Rates and Monetary Amounts Bill B34—2026, National Treasury 2026 draft tax bills