This article will count 0.25 units (15 minutes) of unverifiable CPD. Remember to log these units under your membership profile.
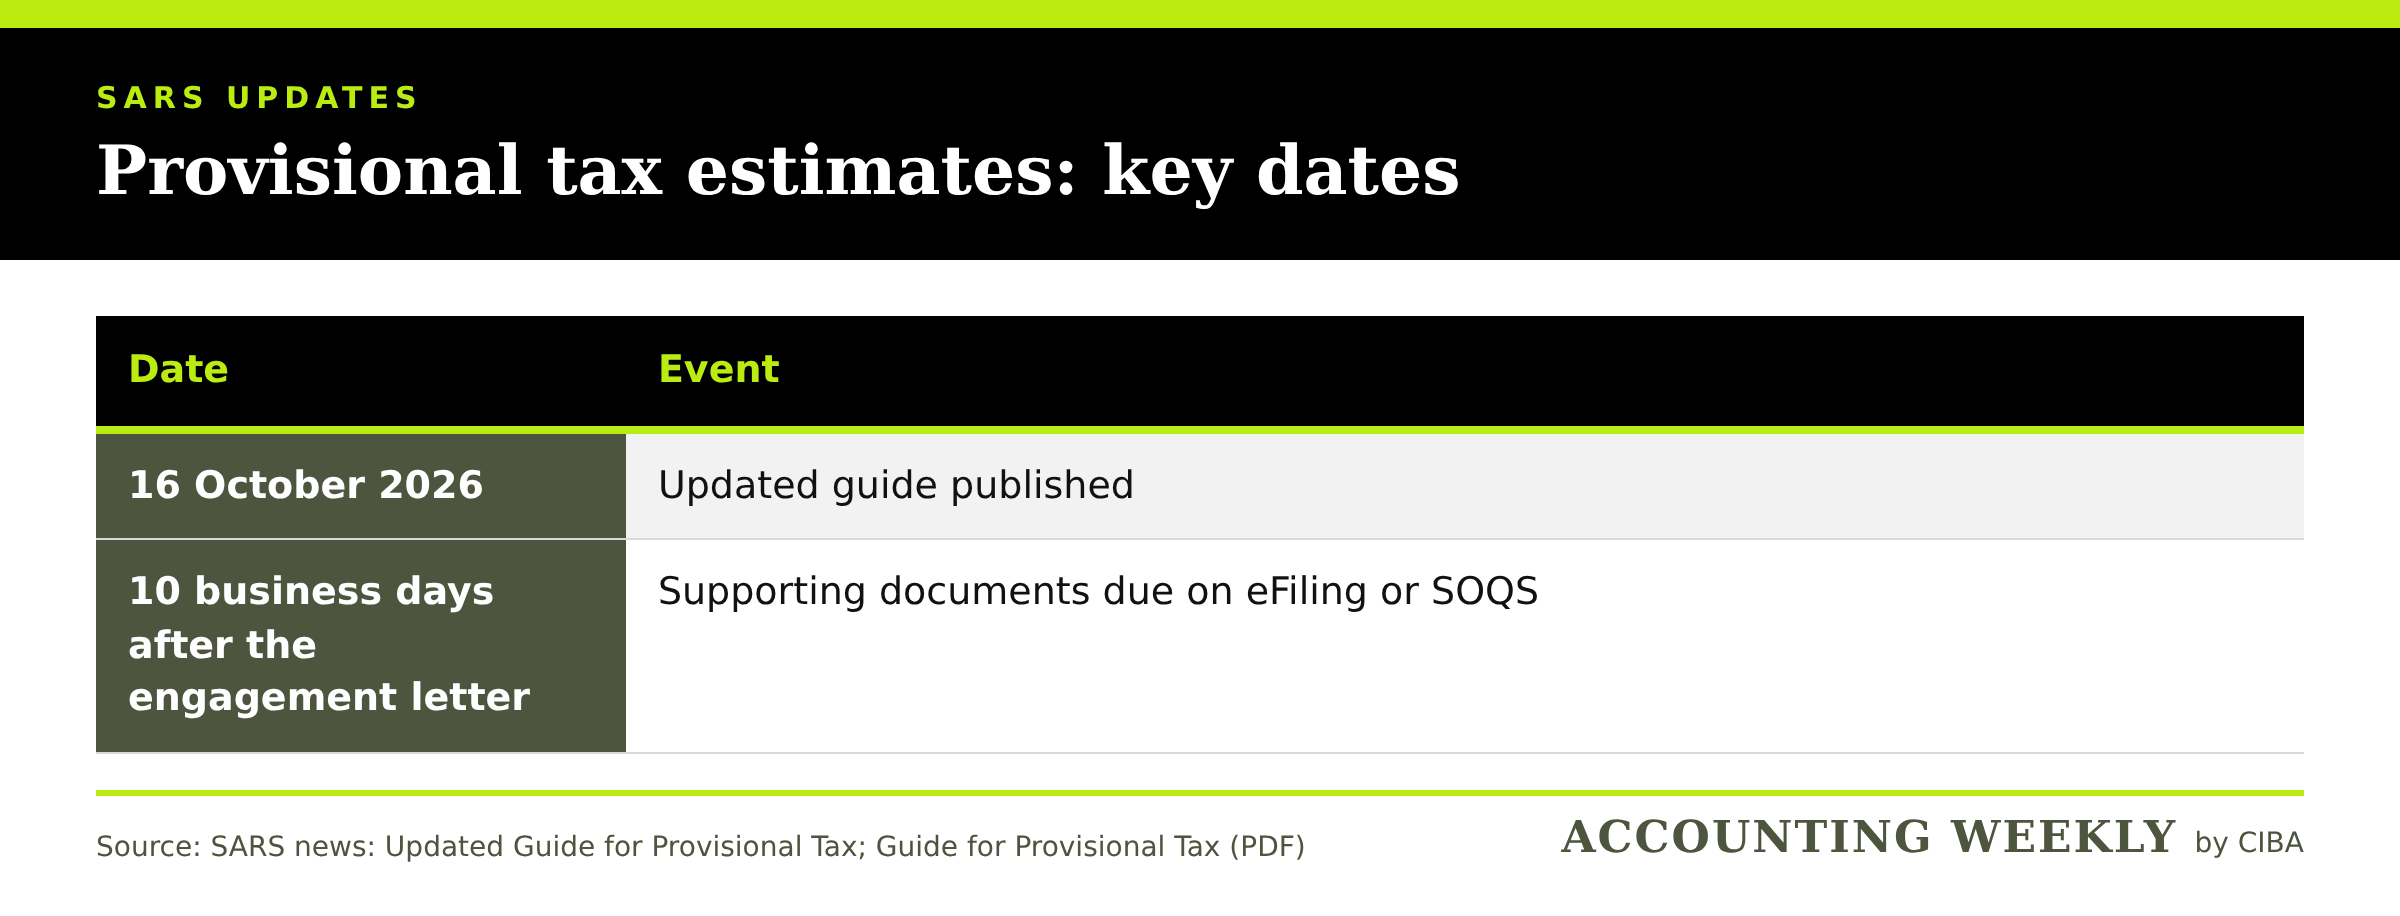
SARS updated its Guide for Provisional Tax (GEN-PT-01-G01) on 16 October 2026. The update explains how SARS will challenge a provisional taxpayer’s estimate of taxable income under paragraph 19(3) of the Fourth Schedule to the Income Tax Act, and how long the taxpayer has to respond.
What changed
SARS may ask a provisional taxpayer to justify the estimate, or to give full details of income, expenses or other information.
SARS will send a paragraph 19(3) engagement letter through eFiling and by email, asking for supporting documents.
The taxpayer must upload the documents on eFiling or the SARS Online Query System (SOQS) within 10 business days.
If SARS is not satisfied, it may raise the estimate to an amount it considers reasonable and issue a revised estimate.
The guide states that this increase “is not subject to objection and appeal”.
Who it affects
Provisional taxpayers, including individuals with business, freelance, rental or investment income, companies and trusts, and the practitioners who prepare their IRP6 returns.
Key dates
What this means for accountants and finance professionals
Every estimate needs a paper trail. SARS can ask how an estimate was reached. A working paper that links the estimate to management accounts, prior assessments and known changes is the best answer.
No second chance. An estimate that SARS raises cannot be taken on objection or appeal. The response to the paragraph 19(3) letter is the client’s only opportunity to defend the figure.
Ten business days is short. Practices need a way to spot engagement letters in clients’ eFiling profiles and email quickly, especially in busy periods.
Cash flow. A raised estimate means a higher provisional payment. Finance teams should include that risk in cash-flow forecasts around the IRP6 dates.
What to do
Keep a working paper for every IRP6 estimate that shows how you reached the figure.
Check clients’ eFiling inboxes and email regularly so an engagement letter is not missed.
When a letter arrives, upload the supporting documents within 10 business days.
Explain to clients that a raised estimate cannot be taken on objection or appeal, so the first response to SARS carries the weight.
Sources: SARS news: Updated Guide for Provisional Tax · Guide for Provisional Tax (PDF)