Tax Court: a contract does not make another company's costs deductible
This article will count 0.25 units (15 minutes) of unverifiable CPD. Remember to log these units under your membership profile.
The Tax Court in Johannesburg dismissed a taxpayer's appeal against SARS's refusal of deductions of about R65.6 million for costs it paid on behalf of a related mining company. Judgment in case IT 76811 was delivered on 4 September 2026, and SARS listed it on its website on 8 October 2026.
The facts
The taxpayer, referred to in the judgment as Taxpayer Olie Trading (Pty) Ltd, processes and sells foundry-grade chromite sand. Its group held 74% of Clarisse Mining Limited, which held a mining right in North West.
Under a 2009 offtake agreement, the taxpayer bought Clarisse's chrome ore. Clause 12 made the taxpayer liable for Clarisse's operating costs if the mine went into care and maintenance, meaning a shutdown in which mining stops. The mine went into care and maintenance on 31 August 2017 and stayed there to 2020.
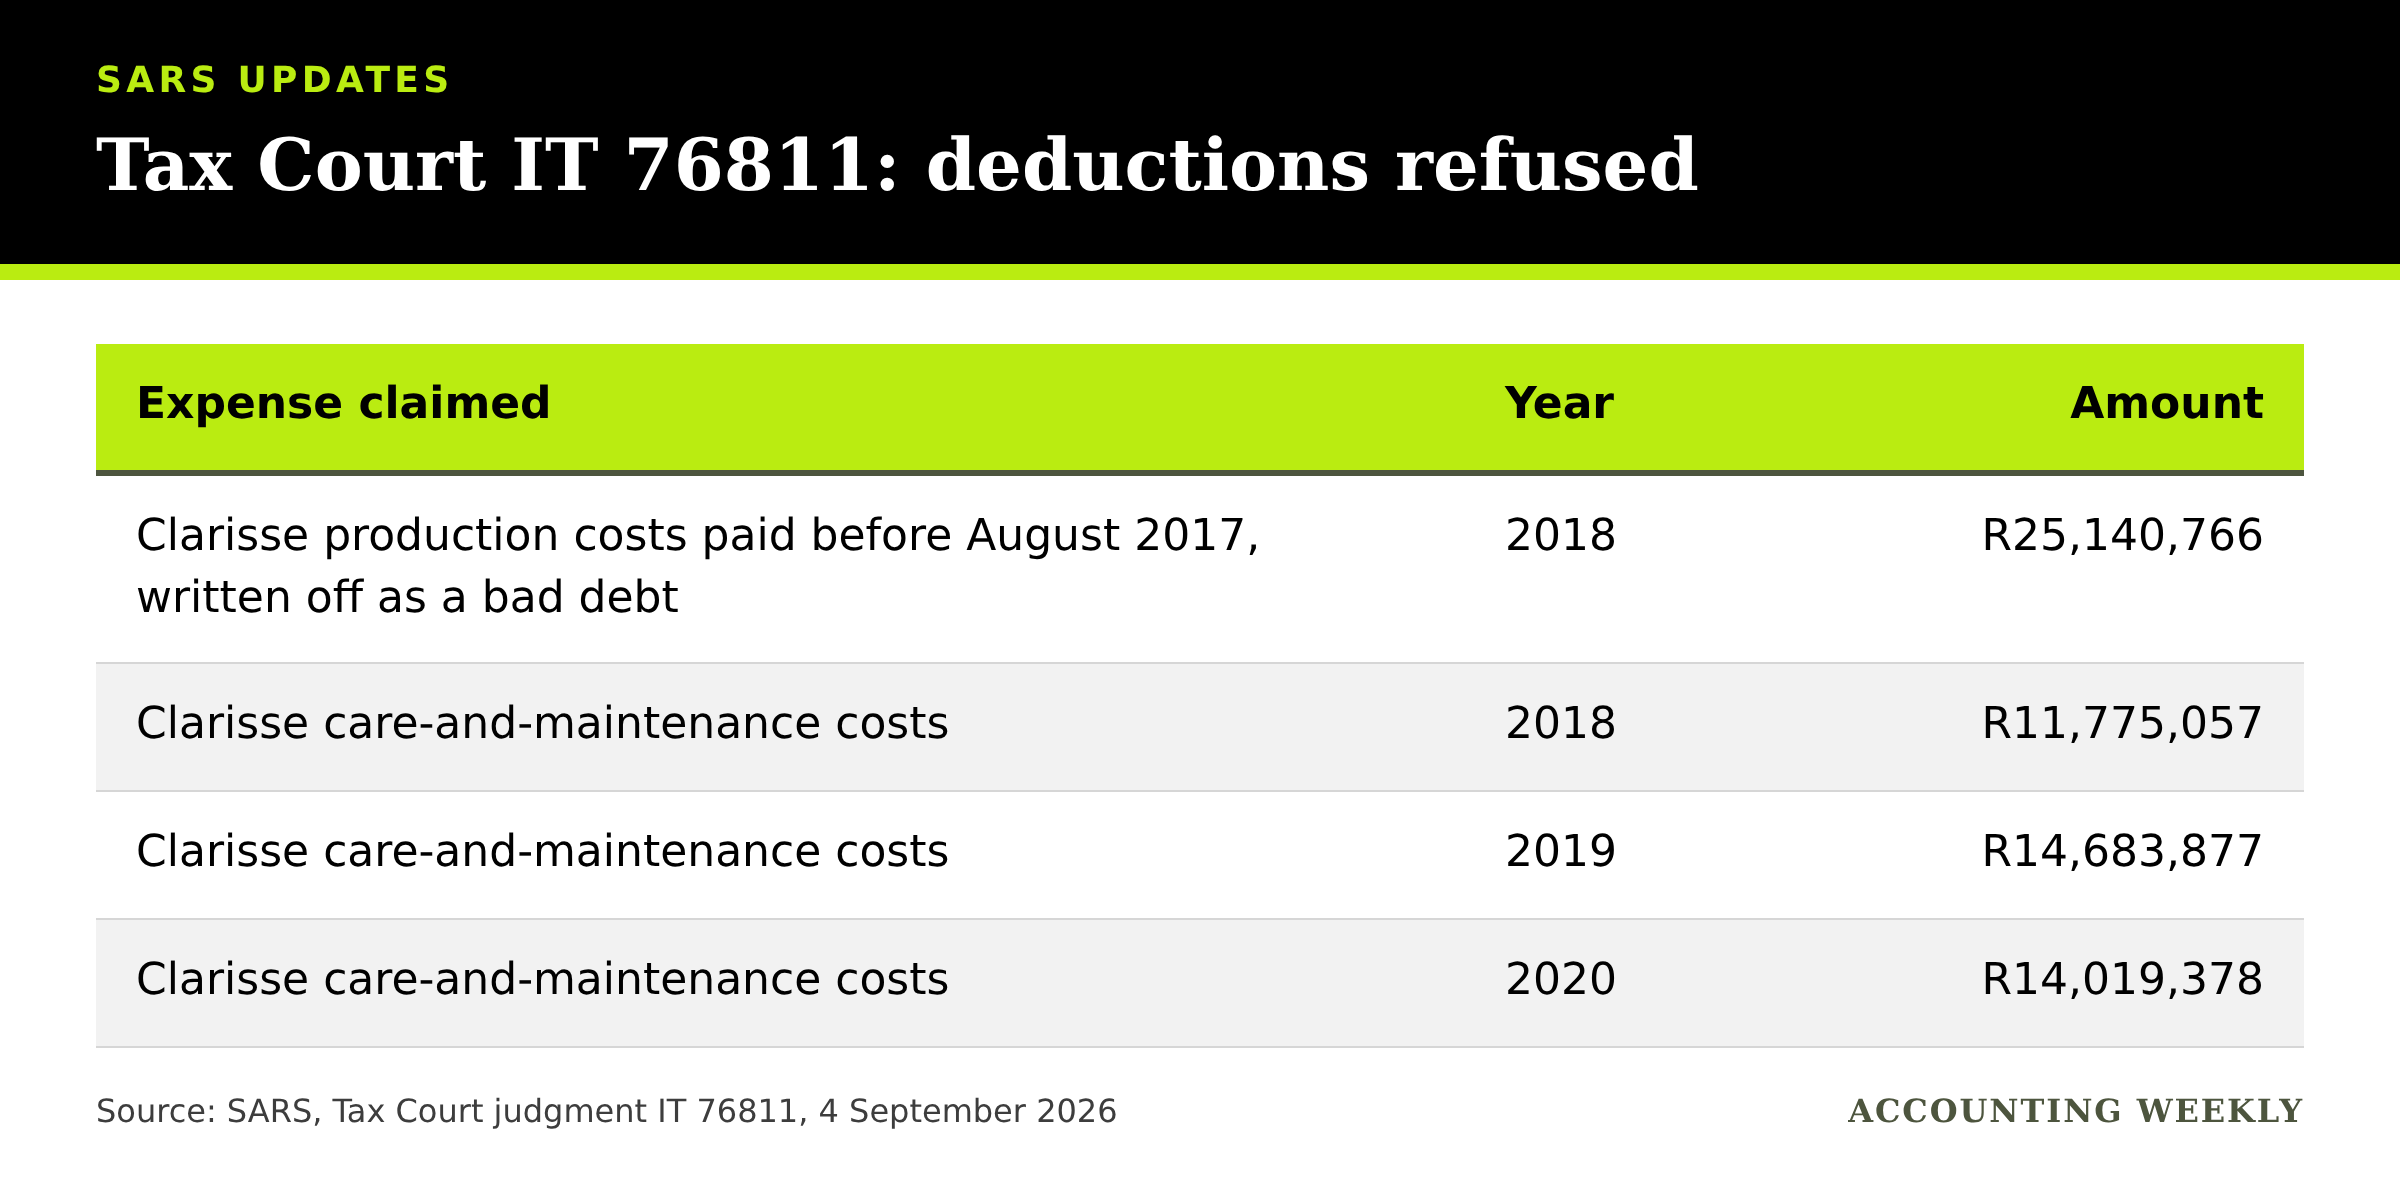
SARS issued additional assessments on 31 August 2022. The taxpayer objected, SARS partly disallowed the objection on 14 March 2023, and the taxpayer appealed on 2 May 2023.
What the court decided
The court, with Senyatsi J presiding, dismissed the appeal and confirmed the additional assessments for 2018, 2019 and 2020 with interest. Its reasons:
The invoices were in Clarisse's name and Clarisse held the supplier contracts, so the costs were Clarisse's. The contract between the companies did not change who incurred them.
The mine was not producing, so the costs preserved a future source of supply and did not produce the taxpayer's income.
Paying another company's operating costs was not part of the taxpayer's trade of selling chromite sand.
The pre-August 2017 costs related to earlier years and could not be deducted in 2018.
Clarisse did not owe the taxpayer these amounts, so the bad debt deduction in section 11(j) did not apply.
Care-and-maintenance costs are normally added to the mine's unredeemed capital expenditure and claimed when mining resumes.
The taxpayer was ordered to pay SARS's costs, including the costs of counsel.
Points for practitioners
A deduction belongs to the company that incurred the expense. The invoices and supplier contracts show who that is.
An agreement to pay another company's costs does not, by itself, make those costs deductible.
The taxpayer carries the burden of proving a deduction.