SARS deadlines: 22 October 2026 to 22 January 2027
This article will count 0.25 units (15 minutes) of unverifiable CPD. Remember to log these units under your membership profile.
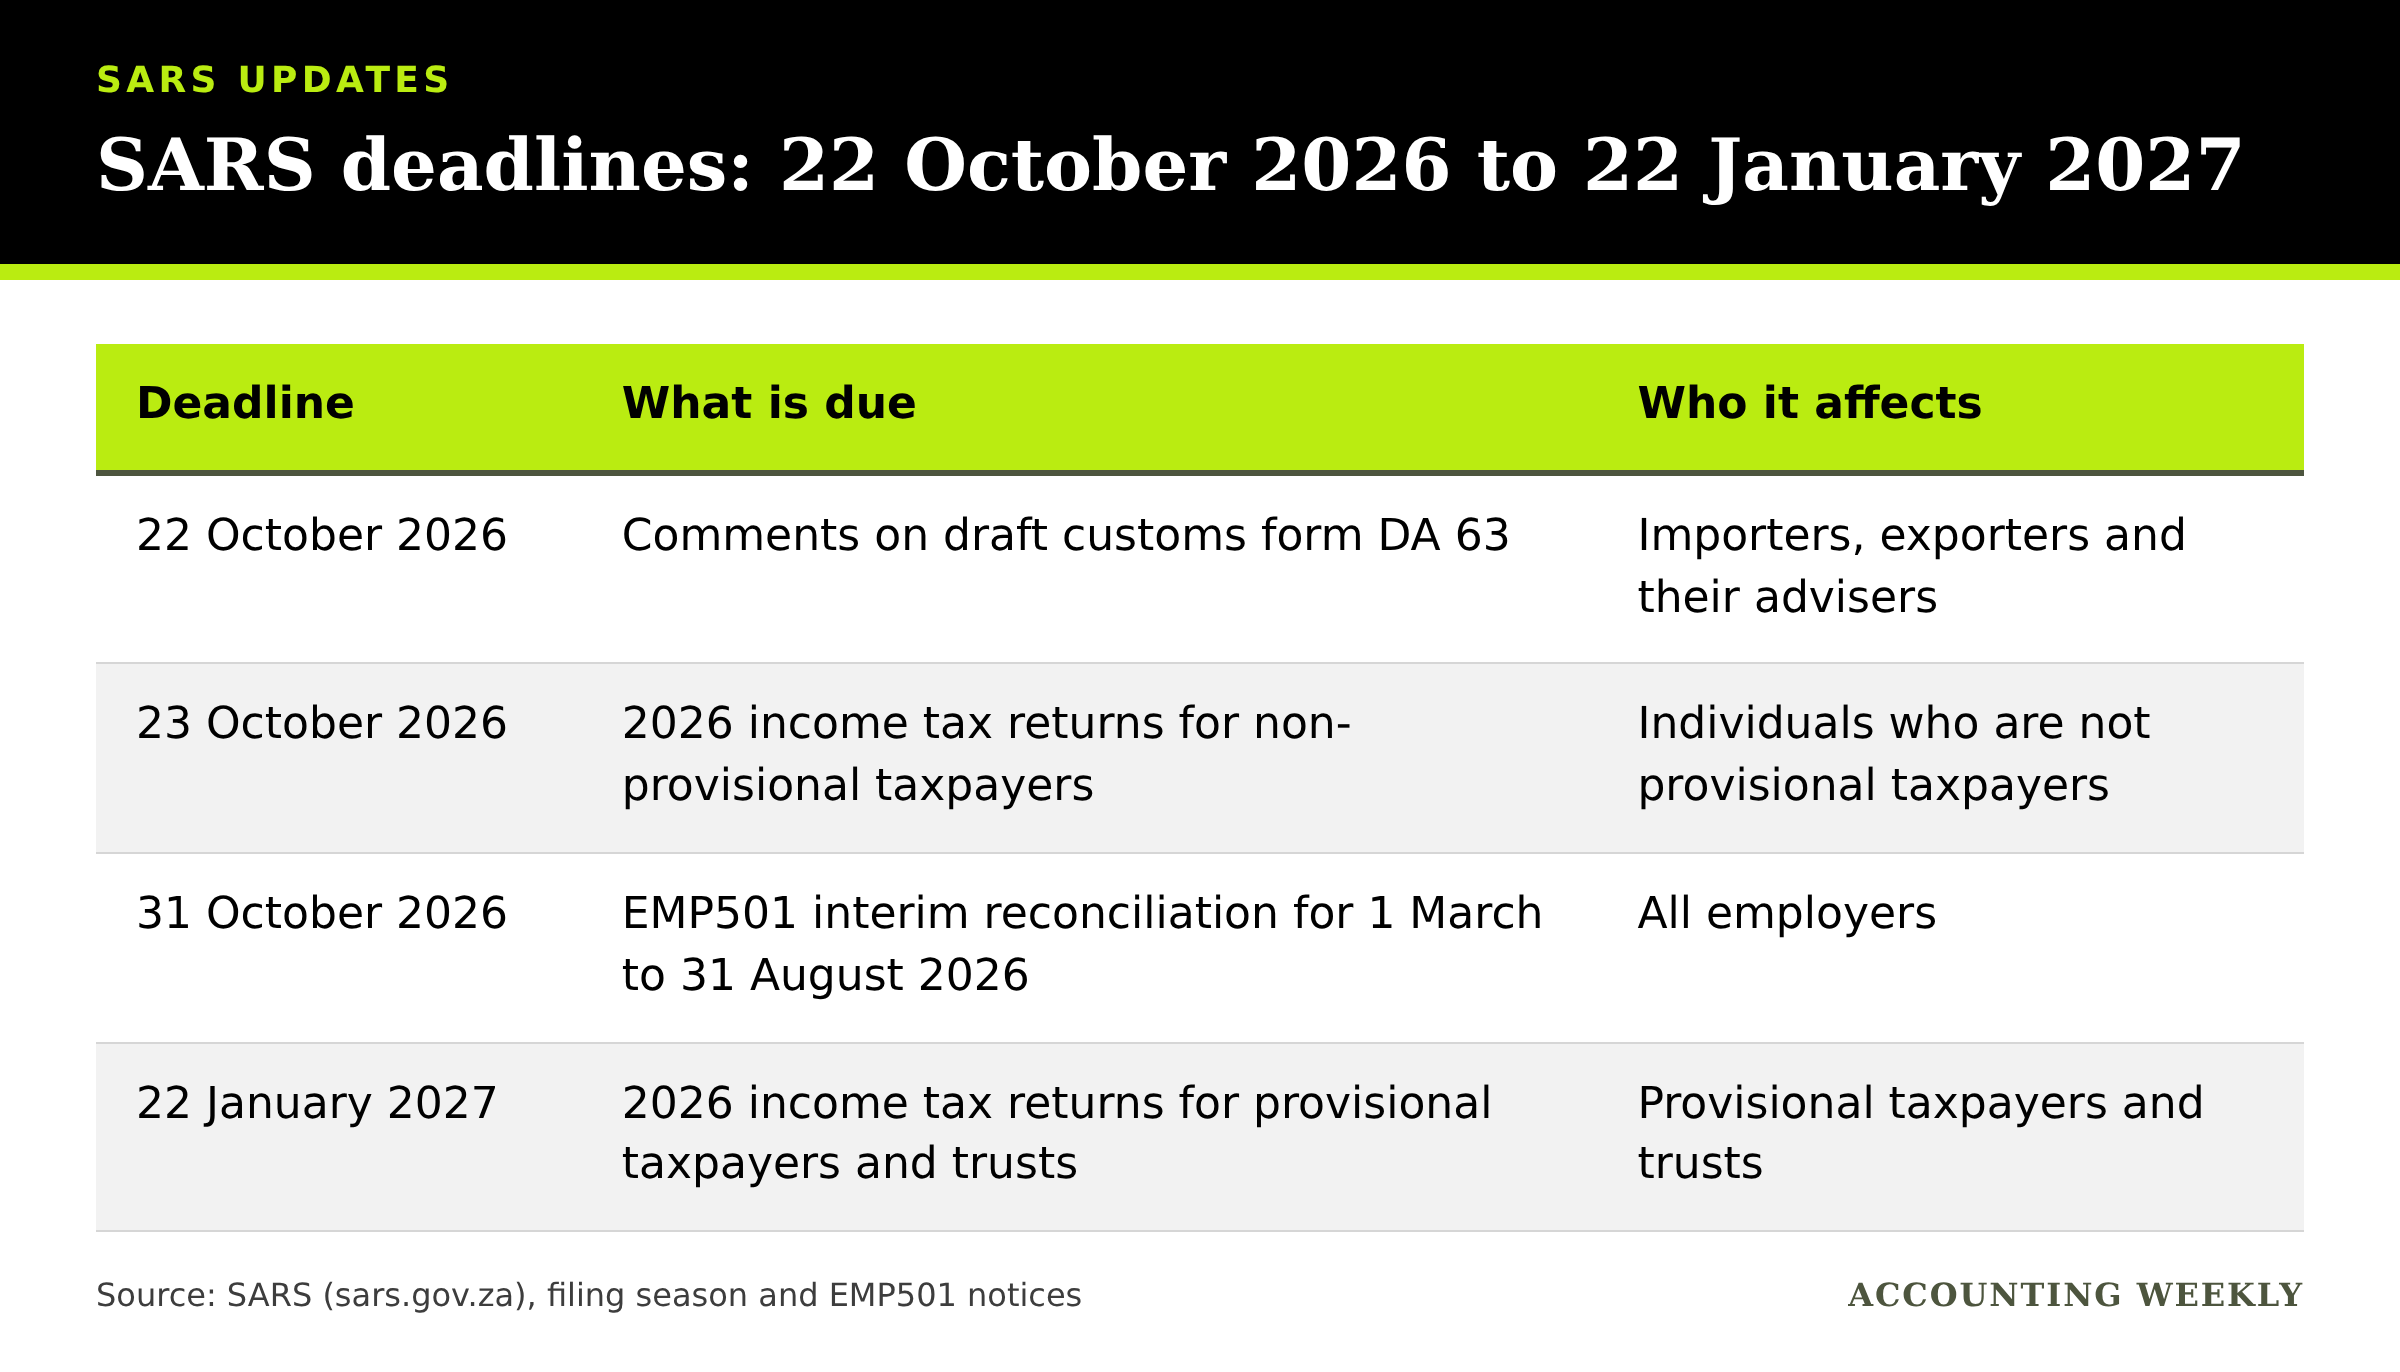
Four SARS deadlines fall between now and January 2027. Two of them, for non-provisional taxpayers and the EMP501 interim reconciliation, fall in October 2026.
23 October 2026: non-provisional taxpayers
The 2026 filing season for non-provisional taxpayers runs from 13 July to 23 October 2026. Returns for these taxpayers must be filed by 23 October 2026.
31 October 2026: EMP501 interim reconciliation
The interim reconciliation covers 1 March to 31 August 2026. The submission window opened on 21 September 2026. SARS says employers "must submit an accurate EMP501 using e@syFile Employer or SARS eFiling by 31 October 2026".
Submission channels:
e@syFile Employer: open to all employers, with no limit on the number of certificates.
eFiling: up to 50 IRP5/IT3(a) certificates per submission.
SARS branch: by appointment, for employers with five or fewer certificates who cannot use either online channel.
What SARS requires:
PAYE, UIF and SDL in the reconciliation must match the EMP201 returns already submitted.
Employees' income tax reference numbers must be on their IRP5 certificates. SARS has enforced this since the February 2026 reconciliation.
Penalties and interest must not be included in the payments declared.
Software: SARS released e@syFile Employer version 8.0.2_418 on 2 October 2026 with an updated EMP501 form. Users moving from version 8.0.1 to 8.0.2 must uninstall and reinstall the software from eFiling.
Penalties: according to SARS, a late EMP501 attracts an administrative penalty of 1% of the employer's annual PAYE, rising by 1% for each month it is outstanding, up to 10%. Employers who do not submit may also lose unused Employment Tax Incentive (ETI) credits.
22 January 2027: provisional taxpayers and trusts
The filing season for provisional taxpayers runs from 13 July 2026 to 22 January 2027, and for trusts from 19 September 2026 to 22 January 2027. Under Notice 7958 of 25 September 2026, certain provisional taxpayers who received an automatic assessment also have until 22 January 2027 to request a reduced or additional assessment.
What to do
Check which individual clients are non-provisional and have not yet filed; file before 23 October 2026.
Update e@syFile Employer to version 8.0.2_418.
Reconcile each employer client's EMP201s to the EMP501 and check every employee's income tax number before submitting by 31 October 2026.
Diarise 22 January 2027 for provisional taxpayers and trusts.
Sources: SARS filing season, SARS EMP501 interim declarations, e@syFile release notes, Notice 7958, draft DA 63